Spot the production handoff
When production shifts outside the company’s own facility, update the operating description with locations, materials, tooling ownership, quality control, and shipment responsibilities.
The agreement should identify who controls work in process and who carries responsibility when materials or finished goods are damaged.
Gather the working documents
Keep the manufacturing agreement, insurance requirements, tooling list, inventory reports, certificates, and quality procedures in one file.
Record the entity names, addresses, and the exact operation covered by each agreement.
- Customer-owned tooling and property
- Inventory at each location
- Indemnity and insurance clauses
Compare contract and policy language
Review property-in-transit, off-premises property, products-completed operations, contractual liability, and additional-insured requests against the forms and endorsements.
A certificate cannot add coverage or change the underlying policy.
Update after scale changes
Revisit the file when production volume, countries, suppliers, or testing responsibilities change.
Policy wording, declarations, endorsements, and facts control any outcome.
Map property and responsibility at every production stage
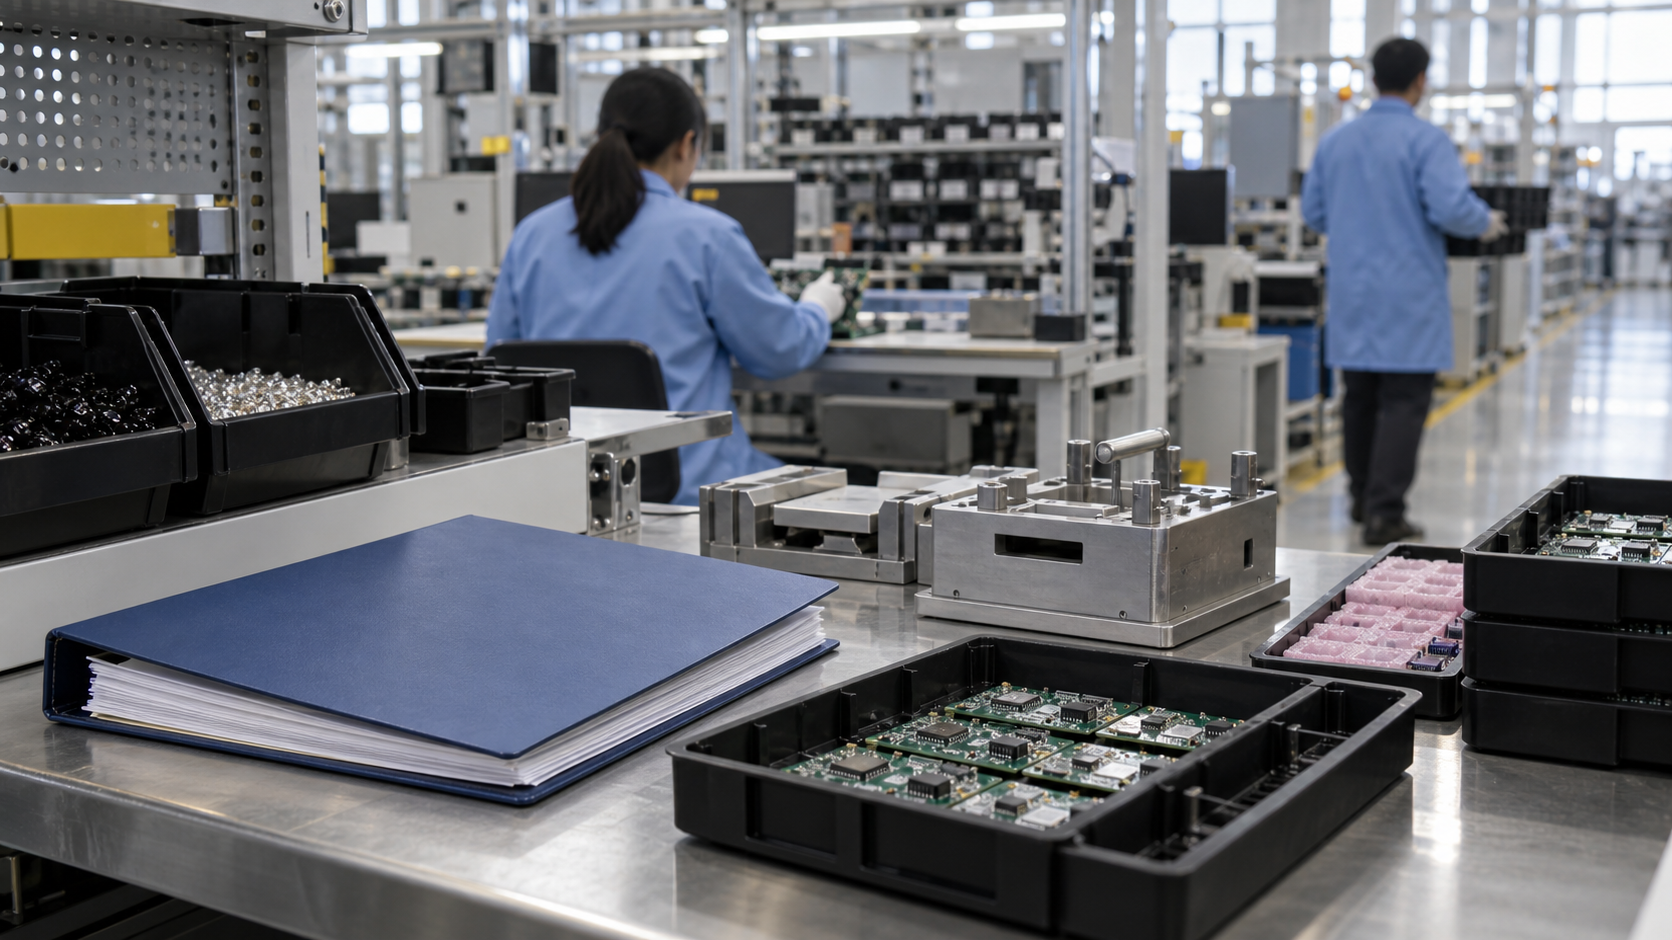
A contract-manufacturing insurance file should identify raw materials, work in process, finished goods, test fixtures, molds, and customer-owned property at each facility. Record when title changes, who physically controls the items, who selects the freight carrier, and which party must report damage or delay.
Do not collapse those facts into a single inventory total. A component at a supplier, a customer-owned tool at a machine shop, and finished goods awaiting pickup can have different contract responsibilities and different insurance questions.
Review supplier evidence without overreading it
Collect the supplier’s certificate only as one part of the file, then identify the actual agreement and any relevant endorsement request. Check the entity name, address, scope of work, expiration date, and whether the contract asks for ongoing or completed-operations status.
Where a supplier cannot provide a requested term, treat that as a commercial and risk-allocation decision. Potrero Risk can help compare the request with available business insurance terms, but no website guide can decide the supplier’s obligations or the policy outcome.