San Francisco · Commercial insurance brokerage
Commercial insurance for manufacturers and hardware startups.
We find insurance for your production equipment, prototypes, and product liability. We handle the submission and market follow-up, then explain how the proposed policies cover your operation.
Our work for business customers
Getting insured
You run production. We work through the insurance.
We learn the operation
We ask what you make, where production happens, and what your contracts require. Your current insurance gives us a starting point.
We request quotes
We prepare the equipment and operations information for the market and follow up on the questions needed to obtain terms.
We explain the choices
We compare the offered policies with your property and customer obligations, then walk you through the price and coverage tradeoffs.
Property insurance
Insure the equipment your production depends on.
A new machine, rented tooling, or stock at another location changes what needs insuring. We work through the equipment schedule and compare property terms, including the values and locations the policy uses.
The submission describes what you actually make
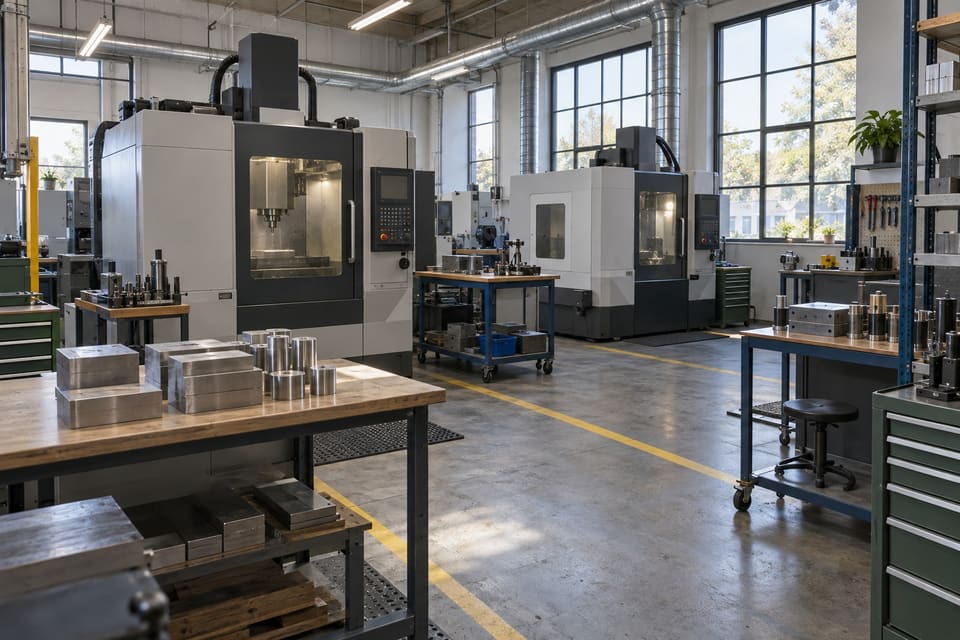
A general trade label leaves out the processes underwriters price on. We set out the materials, machinery, and finishing work so the account is quoted against the real operation.
Equipment away from the workshop
Tooling at a supplier, a machine on loan, and a unit shipped for testing sit outside a fixed-address schedule. We record where property goes and check where the proposed coverage applies.
Customer agreements read before the quote
Purchase orders and supply agreements set limits, additional-insured status, and product terms. We compare what those documents require against what each proposal grants.
Coverage we source
Business insurance from the floor to delivery.
Choose a policy to read about
Commercial property
We compare insurance for your workshop, machinery, and stock, including terms for the income lost after covered damage.
What we work through
- We account for the building and its contents
- We check how the equipment is valued
- We compare cover for repairs and lost income
Inland marine
We seek coverage for portable tools, demonstration units, and equipment in transit or at customer locations.
What we work through
- We quote the equipment’s full journey
- We establish what you need insured
- We explain theft, testing, and storage conditions
General liability
We compare liability options for customer injuries, property damage, and claims involving your finished products.
What we work through
- We present your products accurately to the market
- We check customer insurance requirements
- We explain the limits of product liability cover
Manufacturing and hardware
Coverage for your stage of production.
Policy and contract review
We read the policy before you put it to work.
When a customer asks for insurance or a prototype goes out for testing, we check your policy against the work ahead. We explain the exclusions and limits that matter, identify requirements that need different wording, and pursue the available options.
Talk to us about your coverage
Get commercial insurance for what you make.
Tell us about your production setup and insurance deadline. We’ll prepare the submission and compare the market’s response with you.
Potrero Hill
Insurance for production in San Francisco and beyond the shop.
We work with San Francisco manufacturers and hardware businesses whose equipment and products travel beyond their own premises. We account for customer trials, outside assembly, and installation work in the submission so the market can quote the operation you actually run.
Before you buy
Know how the insurance fits your equipment.
Can you insure a prototype at a customer site?
We can seek options for a prototype away from your premises. We check whether the property policy extends to that location or whether an inland marine form is needed, including the trial activities, time away, and value of the unit.
How do you work out equipment values for a quote?
We help organize the equipment list and review the basis for the reported values. Purchase price may differ from replacement cost, especially when tooling or installation is involved. We compare those figures with the valuation and coinsurance terms offered.
Can you help meet a customer’s insurance requirements?
Yes. We read the insurance clause and compare it with your policy or proposed terms. If the customer asks for additional-insured status or products-completed operations coverage, we check the relevant endorsements. A certificate alone does not add coverage.